Skip to content
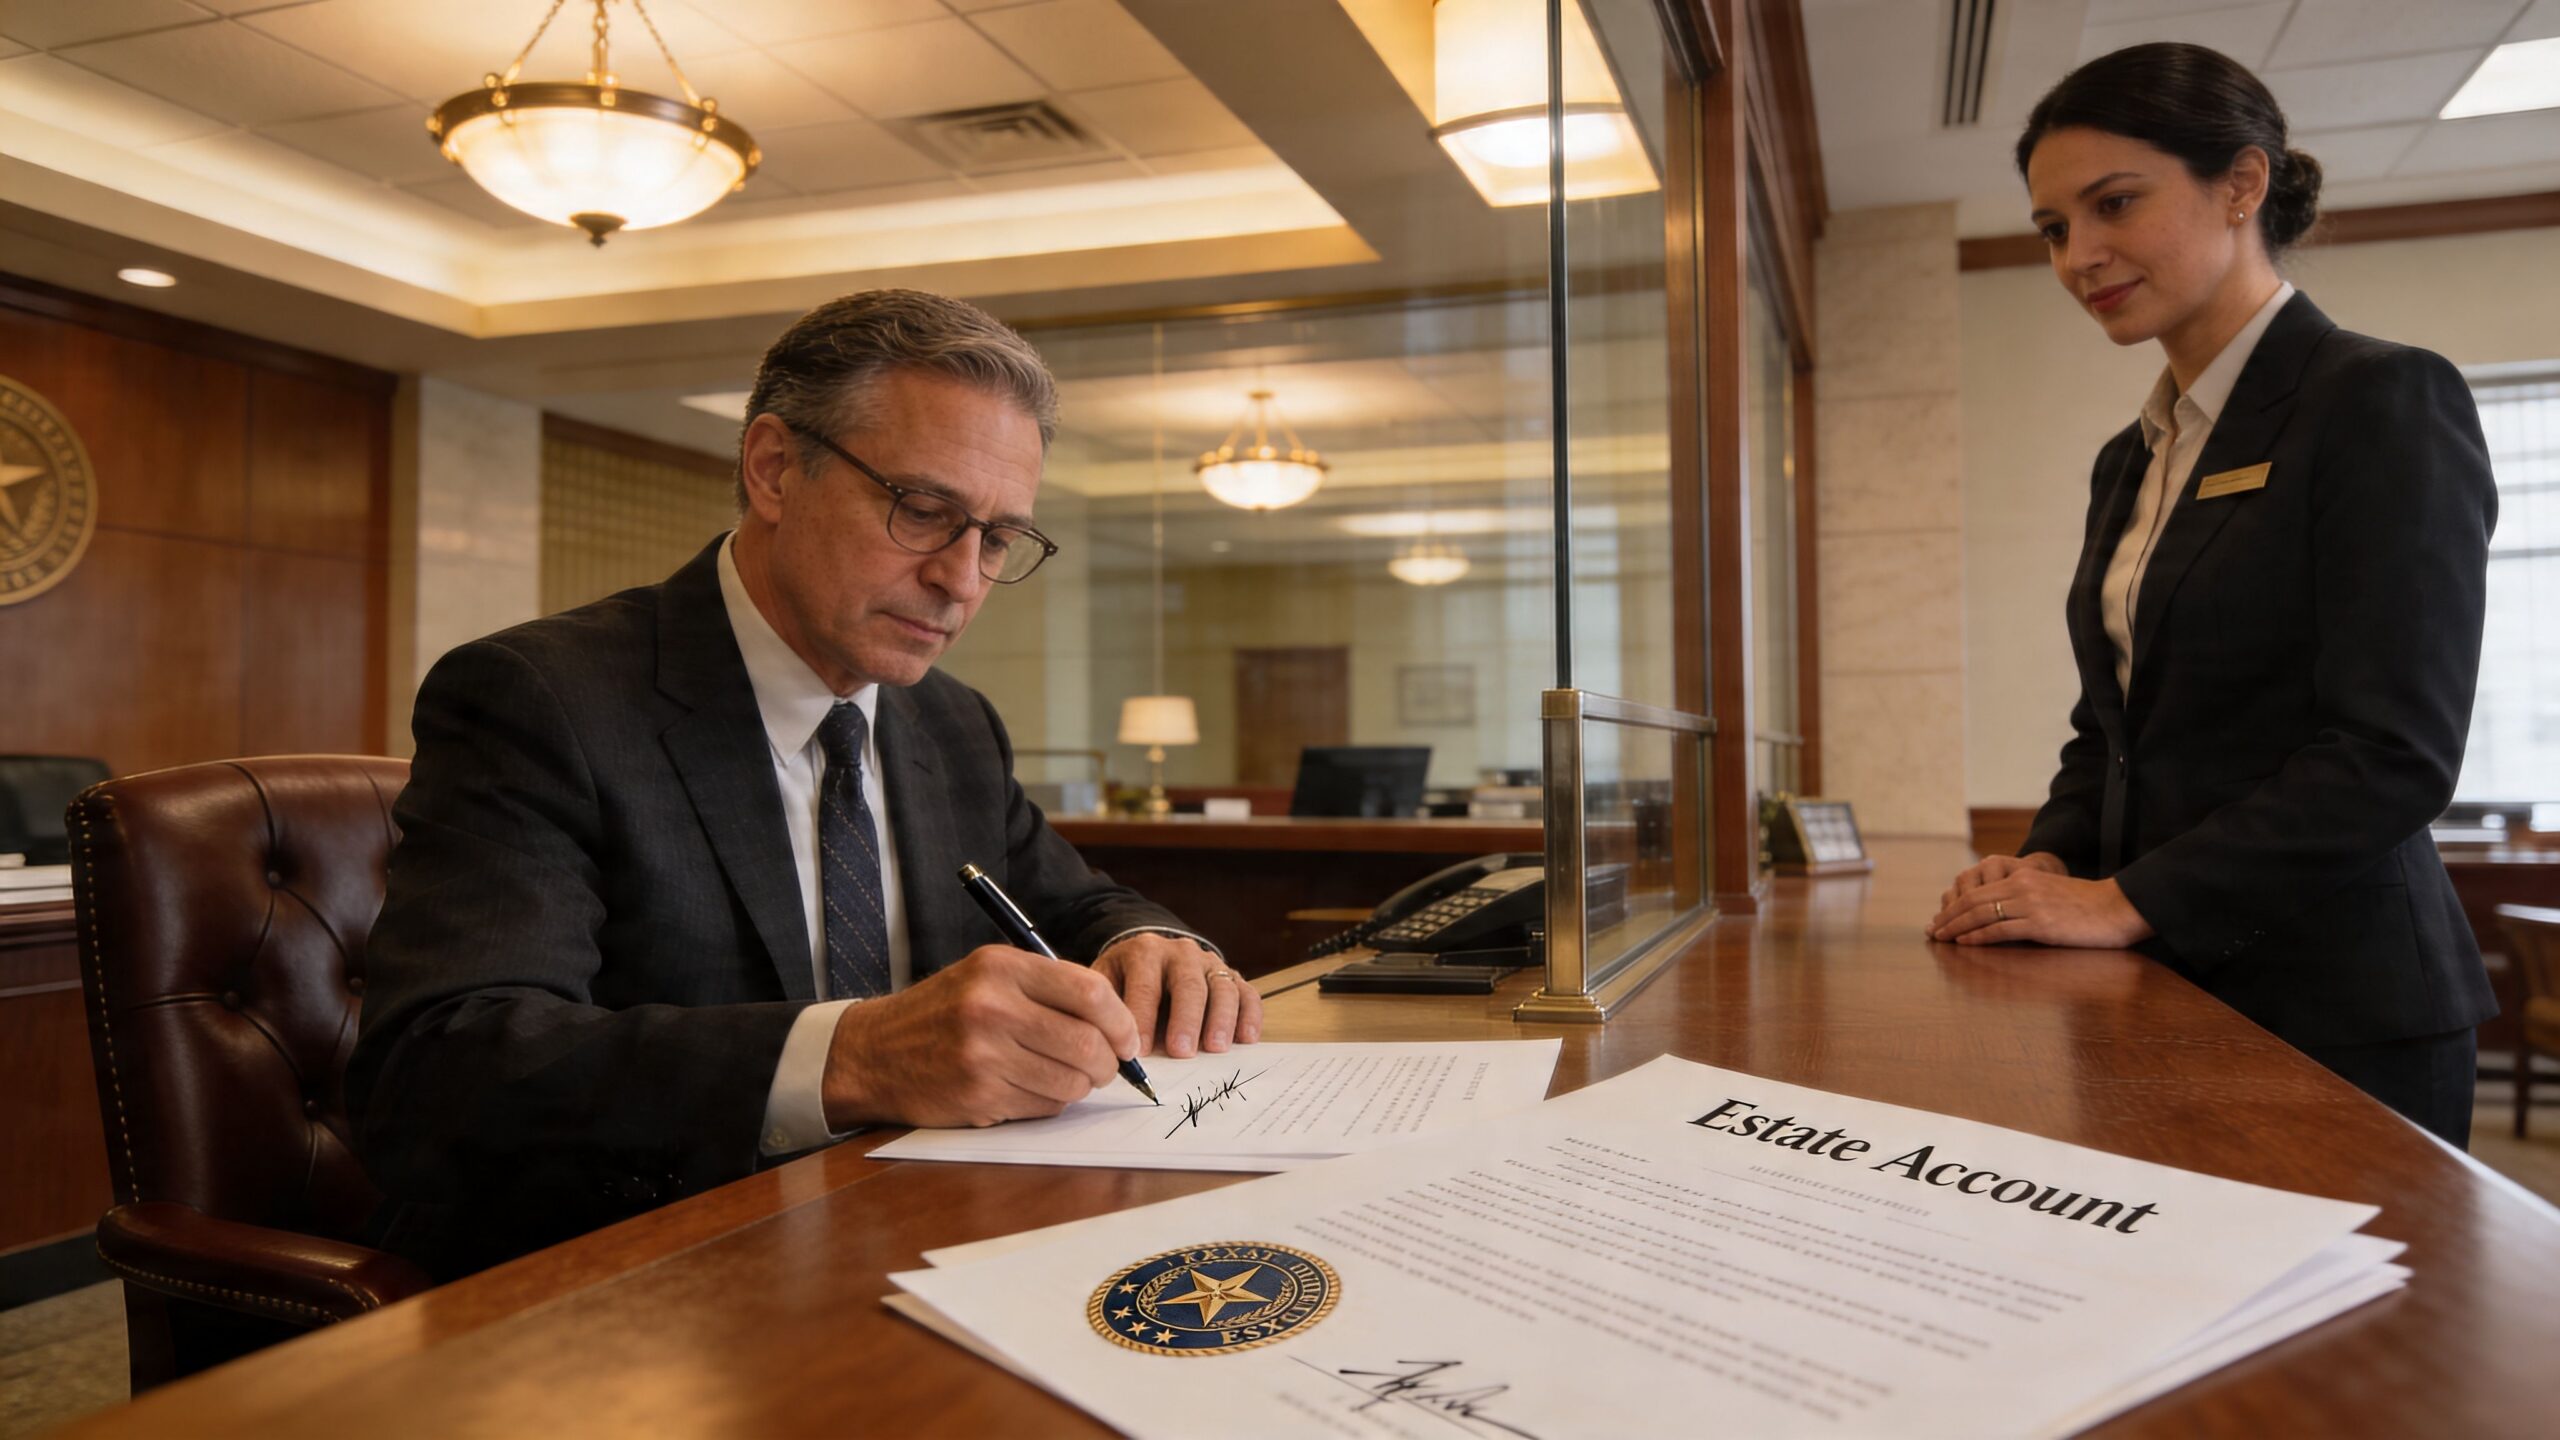
Probate estate account closing is one of the final and most important steps in administering an estate because it generally occurs only after the estate’s financial responsibilities have been addressed and the remaining assets are ready for final distribution. While many people focus on gathering assets or paying debts early in probate, the process of closing an estate bank account often signals that the administration is approaching completion. Understanding when this step occurs and why it matters can help executors, beneficiaries, and families better navigate the probate process.
Imagine that Sarah has been appointed as the independent executor of her father’s estate. Soon after receiving authority from the probate court, she opens an estate bank account to collect incoming funds, pay approved expenses, and keep estate finances separate from her personal accounts. Months later, after taxes have been addressed, creditors have been handled, and distributions are nearly complete, Sarah begins asking another important question: when should the estate bank account actually be closed?
That question illustrates why understanding probate estate account closing is so important. Closing an estate account too early could create unnecessary complications if additional bills or refunds arise, while keeping it open longer than necessary may delay the completion of the administration.
From an analytical perspective, estate account closing represents the financial conclusion of the probate administration rather than simply closing a bank account.
Understanding Probate Estate Account Closing
Before discussing the timing, it helps to understand what probate estate account closing generally means.
An estate bank account is typically opened after an executor or personal representative receives legal authority to administer the estate.
Rather than using personal banking accounts, estate funds are commonly deposited into a separate account established solely for estate administration.
Throughout probate, this account may receive:
- Proceeds from asset sales
- Refunds
- Dividend payments
- Rental income
- Other estate-related funds
Likewise, the account may be used to pay:
- Approved debts
- Administrative expenses
- Taxes
- Court costs
- Professional fees
- Final beneficiary distributions
The account generally remains open until these financial responsibilities have been substantially completed.
Why Estate Bank Accounts Matter
Maintaining a separate estate account promotes financial organization throughout probate.
Instead of mixing estate funds with personal finances, the executor can clearly document every transaction involving estate property.
A dedicated account often helps with:
- Accurate accounting
- Recordkeeping
- Transparency
- Tax reporting
- Beneficiary communication
Clear financial records also simplify the preparation of any final accounting that may be required during probate.
Opening the Estate Account
Before probate estate account closing becomes relevant, an estate account generally must first be established.
Although banking procedures vary, institutions commonly request documentation demonstrating the executor’s legal authority.
Depending on the circumstances, documentation may include:
- Letters Testamentary
- Letters of Administration
- Employer Identification Number (EIN)
- Court documents
- Personal identification
Once established, the account becomes the central location for most estate-related financial activity.
Why the Account Should Remain Separate
One of the most important responsibilities of an executor involves separating estate finances from personal funds.
Maintaining separate accounts helps avoid confusion regarding:
- Deposits
- Withdrawals
- Expense payments
- Asset distributions
- Financial reporting
Good separation also supports accurate documentation if beneficiaries or the probate court later review the estate’s financial records.
Paying Estate Obligations
An estate account serves as the primary source for paying many financial obligations arising during probate.
Depending on the administration, payments may include:
- Funeral-related expenses when appropriate
- Outstanding debts
- Utility bills
- Property expenses
- Professional service fees
- Court costs
- Tax obligations
Each payment should generally be supported by appropriate documentation and reflected in the estate’s financial records.
Receiving Estate Income
Estate administration sometimes continues for months or longer.
During that period, the estate may continue receiving funds.
Examples include:
- Interest payments
- Stock dividends
- Rental income
- Insurance proceeds
- Tax refunds
- Other lawful receipts
These funds are commonly deposited into the estate account before final distribution occurs.
Real-Life Example
Consider a hypothetical executor named Michael.
After opening an estate bank account, he deposits proceeds from the sale of the decedent’s vehicle, collects a tax refund issued several months later, and uses the account to pay approved expenses associated with the administration.
Only after confirming that outstanding obligations have been addressed and the remaining assets are ready for distribution does Michael begin planning the probate estate account closing process.
His experience demonstrates that closing the account is typically one of the final financial steps rather than one of the first.
Why Timing Is Important
Closing an estate account at the proper time requires careful planning.
If the account closes too early, later-arriving obligations may create administrative challenges.
Examples could include:
- Unexpected invoices
- Delayed refunds
- Additional administrative expenses
- Banking adjustments
- Tax-related matters
Keeping the account available until financial obligations have been substantially completed often promotes a smoother conclusion to probate.
Maintaining Accurate Records
Careful documentation remains important throughout estate administration.
Helpful records may include:
- Monthly bank statements
- Deposit records
- Cancelled checks
- Electronic payment confirmations
- Receipts
- Expense invoices
- Distribution records
Organized financial documentation often simplifies communication with beneficiaries while supporting accurate estate administration.
Communication With Beneficiaries
Financial transparency frequently reduces misunderstandings during probate.
Executors often communicate regarding:
- Estate expenses
- Funds received
- Expected distributions
- Administrative progress
- Remaining obligations
While communication practices vary depending on the estate, keeping beneficiaries informed often encourages confidence in the administration process.
Why Every Estate Is Different
No two probate matters follow exactly the same timeline.
Some estates involve only a few straightforward transactions.
Others include numerous financial accounts, investment assets, business interests, or real property requiring extended administration.
Because every estate presents different financial circumstances, probate estate account closing depends upon the completion of the estate’s specific obligations rather than a fixed calendar date.
Preparing for Probate Estate Account Closing
As estate administration progresses, the executor eventually begins preparing for probate estate account closing.
This preparation typically involves reviewing the estate’s financial activity to determine whether major administrative responsibilities have been completed.
Depending on the circumstances, the executor may review:
- Outstanding account balances
- Remaining obligations
- Pending deposits
- Uncashed checks
- Expected refunds
- Final distributions
Careful review helps reduce the possibility of overlooking important financial matters before the account is closed.
Confirming Outstanding Debts Have Been Addressed
One important consideration involves determining whether known estate obligations have been resolved.
Depending on the administration, these obligations may include:
- Approved creditor claims
- Utility expenses
- Property maintenance costs
- Insurance premiums
- Professional service fees
- Administrative expenses
Reviewing these financial responsibilities before probate estate account closing helps ensure the estate administration moves toward an orderly conclusion.
Final Tax Considerations
Tax matters frequently remain part of estate administration until late in the probate process.
Depending on the estate, financial obligations may include:
- Final individual income tax matters
- Estate-related tax filings
- Property taxes
- Other applicable tax responsibilities
Because tax issues sometimes continue after other administrative tasks have been completed, executors often consider them carefully before closing the estate account.
Completing Beneficiary Distributions
One of the primary purposes of probate administration is distributing remaining estate assets according to the applicable will or governing law.
Once authorized, the executor may distribute the remaining balance after estate obligations have been addressed.
Distributions may involve:
- Cash payments
- Investment proceeds
- Sale proceeds
- Other remaining estate funds
Maintaining accurate documentation of every distribution helps create a complete financial record for the estate.
Preparing the Final Accounting
Many estates require a final review of financial activity before administration concludes.
A final accounting commonly summarizes:
- Beginning account balances
- Estate income received
- Expenses paid
- Administrative costs
- Beneficiary distributions
- Remaining balances
Preparing this information allows interested parties to understand how estate funds were managed throughout the probate process.
Reconciling the Estate Account
Before probate estate account closing, executors often reconcile the account to confirm that financial records accurately match the bank’s records.
Reconciliation may involve reviewing:
- Monthly statements
- Electronic transfers
- Deposits
- Outstanding checks
- Bank service charges
- Interest earned
Resolving discrepancies before closing the account helps create complete and accurate financial documentation.
Retaining Important Records
Closing the estate bank account does not eliminate the need to preserve financial records.
Executors commonly retain documents such as:
- Bank statements
- Deposit records
- Cancelled checks
- Tax documents
- Receipts
- Court filings
- Distribution records
- Financial correspondence
Maintaining organized records may prove helpful if questions arise after the estate administration has concluded.
Real-Life Example
Imagine an executor named Daniel administering his aunt’s estate.
Throughout probate, Daniel uses the estate account to receive proceeds from the sale of personal property, pay approved expenses, satisfy administrative costs, and distribute the remaining funds to beneficiaries.
Before requesting probate estate account closing, he carefully reviews the account to confirm that all checks have cleared, no expected refunds remain outstanding, and every financial transaction has been properly documented.
Because he waited until the estate’s financial responsibilities had been substantially completed, the account can be closed in an orderly manner with complete supporting records.
Practical Considerations for Executors
Managing an estate account requires attention throughout the administration process.
Helpful practices often include:
- Recording every transaction promptly
- Keeping receipts for all payments
- Reviewing monthly statements
- Maintaining separate estate finances
- Tracking pending obligations
- Preserving electronic and paper records
Consistent organization throughout probate often makes the final account-closing process much simpler.
Avoiding Common Administrative Challenges
Although every estate differs, certain administrative issues may complicate probate estate account closing if not addressed carefully.
Examples include:
- Incomplete financial records
- Unrecorded transactions
- Outstanding payments
- Uncashed distribution checks
- Missing receipts
- Delayed deposits
Careful financial management throughout the administration process helps reduce these challenges while supporting accurate estate records.
Why Professional Guidance May Be Helpful
Some estates involve relatively straightforward financial activity.
Others include complex investment portfolios, closely held businesses, multiple real estate transactions, or ongoing income-producing assets.
In more complicated administrations, executors sometimes work with professionals such as:
- Probate attorneys
- Certified public accountants
- Financial advisors
- Tax professionals
Professional guidance may assist with addressing complicated financial or legal issues while helping ensure estate administration proceeds according to applicable legal requirements.
Every Estate Follows Its Own Timeline
No universal schedule determines exactly when probate estate account closing should occur.
A small estate with limited assets may reach completion relatively quickly.
By contrast, an estate involving numerous creditors, multiple beneficiaries, tax matters, business interests, or property sales may require considerably more time before the financial administration is complete.
From an analytical perspective, the decision to close an estate account depends on the overall progress of the probate administration rather than a predetermined deadline. Careful financial management, complete documentation, accurate accounting, and thoughtful planning all contribute to a smooth transition from active estate administration to the final closing of the estate bank account.

Conclusion
Probate estate account closing represents one of the final financial milestones in the probate process, but it should occur only after the estate’s obligations have been properly addressed. Throughout the administration, the estate bank account serves as the central location for collecting assets, paying approved expenses, managing estate income, and distributing remaining funds to beneficiaries. Closing the account too soon may create unnecessary complications if additional expenses, tax matters, or delayed payments arise, making careful timing an important part of successful estate administration.
From an analytical perspective, probate estate account closing reflects the completion of responsible financial management rather than simply terminating a bank account. Accurate recordkeeping, organized documentation, timely payment of obligations, proper beneficiary distributions, and thorough review of the estate’s financial activity all contribute to a smooth conclusion of the probate process. Because every estate presents unique assets, liabilities, and administrative requirements, the appropriate time to close an estate bank account depends on the specific circumstances of the administration and the applicable requirements under probate law.